Credit Counseling vs. Debt Settlement: Which Offers Faster Debt Relief by 2027?
Credit Counseling vs. Debt Settlement: Which Option Offers Faster Debt Relief by 2027?
In today’s complex financial landscape, many individuals find themselves grappling with overwhelming debt. The burden of high-interest rates, multiple creditors, and seemingly endless monthly payments can be incredibly stressful, leading to a desperate search for effective solutions. Two of the most commonly discussed debt relief options are credit counseling and debt settlement. While both aim to alleviate financial strain, their approaches, implications, and timelines for achieving debt freedom differ significantly. As we look towards 2027, understanding which option might offer faster and more sustainable relief is crucial for making informed decisions about your financial future.
Understanding the Debt Landscape: Why Are People Seeking Debt Relief?
Before diving into the specifics of credit counseling and debt settlement, it’s essential to acknowledge the underlying reasons why so many individuals are seeking debt relief options. Economic shifts, unexpected life events, and sometimes, a lack of financial literacy can all contribute to accumulating unmanageable debt. Job loss, medical emergencies, divorce, or even simply relying too heavily on credit cards to cover daily expenses can quickly spiral into a situation where minimum payments are no longer enough to make a dent in the principal.
The average American household carries a significant amount of debt, from credit cards to personal loans, medical bills, and more. This debt can hinder financial growth, prevent individuals from achieving major life goals like homeownership or retirement, and severely impact mental and emotional well-being. Recognizing the severity of the problem is the first step toward finding a viable solution. The goal for many is not just to reduce debt, but to achieve complete financial freedom, ideally within a few years, making the 2027 timeline a relevant benchmark for many.
Credit Counseling: A Structured Path to Financial Wellness
Credit counseling is often the first recourse for individuals who are struggling with debt but still have a reasonable ability to repay what they owe. It involves working with a non-profit credit counseling agency to develop a personalized debt management plan (DMP). The primary goal of credit counseling is to help you repay your debts in full, but under more favorable terms.
How Credit Counseling Works
When you engage with a credit counseling agency, a certified credit counselor will review your entire financial situation. This includes analyzing your income, expenses, assets, and all your outstanding debts. Based on this comprehensive assessment, they will help you create a realistic budget and, if appropriate, enroll you in a Debt Management Plan (DMP).
In a DMP, the credit counseling agency negotiates with your creditors on your behalf to potentially:
- Reduce interest rates.
- Waive late fees.
- Consolidate multiple monthly payments into one manageable payment.
You then make a single, agreed-upon monthly payment to the credit counseling agency, which then distributes the funds to your creditors. This simplifies your payments and often results in lower overall monthly outgoings. A typical DMP lasts between three to five years, meaning that if you start in 2024, you could realistically be debt-free by 2027 or shortly thereafter.
Pros of Credit Counseling
- Lower Interest Rates: Creditors are often willing to reduce interest rates for consumers in a DMP, as they prefer to receive payments rather than have the debt go into default.
- Consolidated Payments: Making one payment to the counseling agency simplifies your finances and reduces the risk of missing payments.
- Improved Financial Literacy: Credit counseling agencies provide valuable education on budgeting, saving, and responsible credit use, fostering long-term financial health.
- Less Damaging to Credit Score: While a DMP might be noted on your credit report, it is generally considered less damaging than other debt relief options like debt settlement or bankruptcy. It shows creditors you are actively working to repay your debts.
- Avoids Collections: Once enrolled in a DMP, collection calls typically cease as creditors are receiving regular payments.
- Repayment in Full: You repay the full principal amount of your debt, which can be a psychological benefit and maintain stronger relationships with creditors.
Cons of Credit Counseling
- Not Suitable for All Debts: DMPs primarily cover unsecured debts like credit cards, medical bills, and personal loans. Secured debts (mortgages, car loans) and student loans are usually not included.
- Requires Discipline: You must adhere to the agreed-upon monthly payment plan for the entire duration of the DMP. Failure to do so can result in creditors revoking the favorable terms.
- Potential Credit Score Impact: While less severe than other options, a DMP can still negatively affect your credit score in the short term, as some accounts might be closed or marked as ‘managed by a credit counseling agency.’
- Fees: While non-profit agencies exist, some may charge modest setup and monthly fees for their services.
- Longer Repayment Period: While faster than struggling on your own, DMPs typically take 3-5 years, which might feel long if you’re looking for immediate relief.
Debt Settlement: Negotiating for a Lower Principal
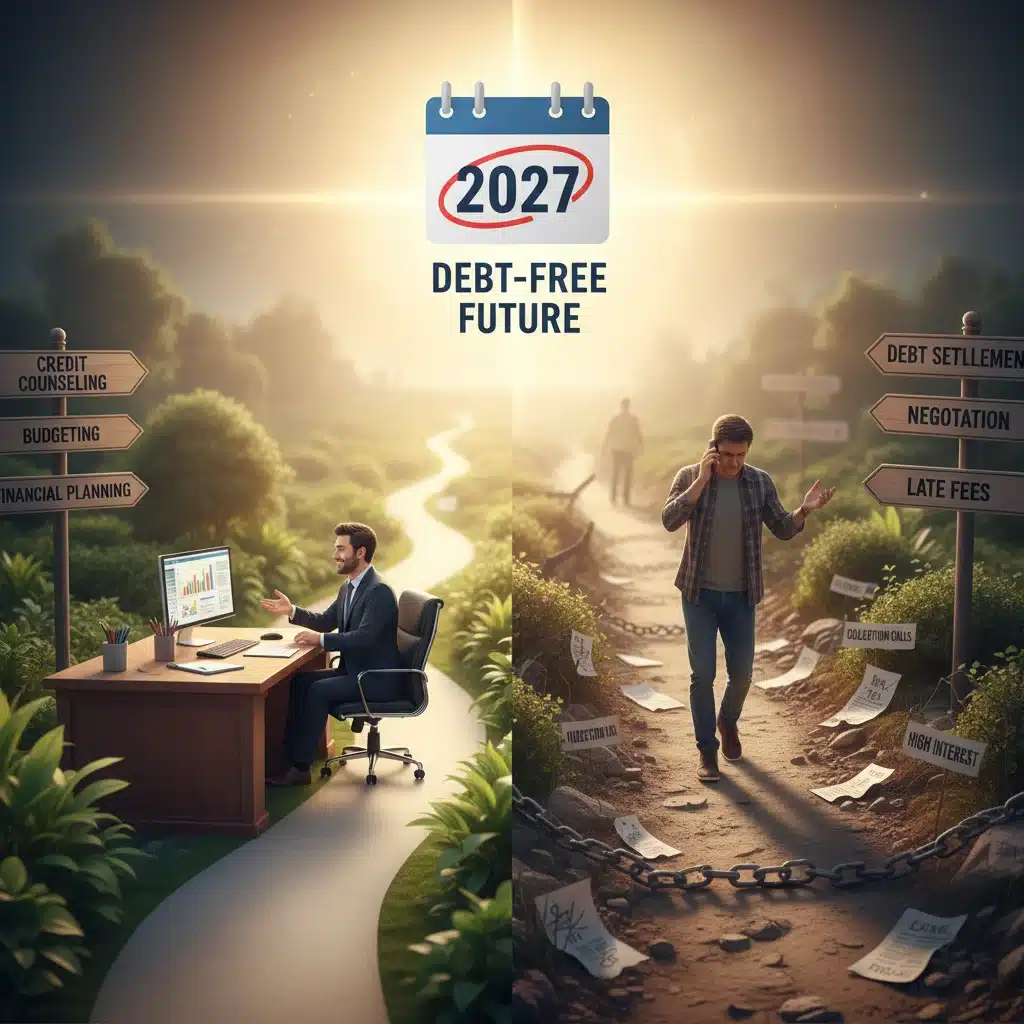
Debt settlement, also known as debt negotiation, is a more aggressive approach to debt relief options. It involves negotiating with creditors to pay a lump sum that is less than the total amount owed. This option is generally pursued by individuals who are severely delinquent on their debts or are on the brink of financial insolvency and cannot realistically afford to repay their debts in full.
How Debt Settlement Works
Debt settlement companies typically advise you to stop making payments to your creditors. Instead, you deposit money into a special savings account, often called an escrow or special purpose account, managed by the settlement company. Once a significant sum has accumulated, the debt settlement company attempts to negotiate with your creditors to accept a reduced amount as full payment for your debt. The creditors agree to this because they would rather recover a portion of the debt than risk losing it all if you declare bankruptcy.
If successful, you pay the agreed-upon reduced amount, and the remaining balance is forgiven. This process can take anywhere from two to four years, potentially offering a quicker path to being debt-free by 2027 if initiated soon.
Pros of Debt Settlement
- Reduced Principal: The most significant advantage is paying back less than what you originally owed, potentially saving a substantial amount of money.
- Faster Debt Elimination: Compared to repaying the full amount through a DMP or minimum payments, debt settlement can lead to being debt-free in a shorter timeframe (typically 2-4 years).
- Avoid Bankruptcy: For those facing severe financial hardship, debt settlement can be an alternative to filing for bankruptcy.
Cons of Debt Settlement
- Significant Credit Score Damage: Stopping payments to creditors will severely damage your credit score, as accounts will go into default, incur late fees, and be reported as delinquent. This negative impact can last for up to seven years.
- Collection Calls and Lawsuits: While you’re accumulating funds for settlement, creditors will likely increase collection efforts, including aggressive phone calls and potentially filing lawsuits.
- Taxable Forgiven Debt: The amount of debt forgiven through settlement may be considered taxable income by the IRS, which can lead to an unexpected tax bill.
- High Fees: Debt settlement companies often charge substantial fees, typically a percentage of the settled debt or the original debt amount, which can eat into your savings.
- No Guarantee of Success: Creditors are not obligated to negotiate or settle, and some may refuse to work with settlement companies.
- Not All Debts Included: Similar to credit counseling, secured debts and student loans are typically not eligible for debt settlement.
Which Option Offers Faster Debt Relief by 2027?
When considering which of these debt relief options offers faster relief by 2027, the answer isn’t as straightforward as it might seem and depends heavily on your current financial situation, the type of debt you have, and your tolerance for risk and credit score impact.
For Moderate Debt and Good Credit (Relatively): Credit Counseling
If you have a manageable amount of unsecured debt, can still make some payments, and want to preserve your credit score as much as possible, credit counseling offers a structured path to being debt-free within the 3-5 year timeframe. Starting a DMP in 2024 means you could realistically be debt-free by 2027 or 2028. This option focuses on responsible repayment and financial education, leading to more sustainable financial habits in the long run.
For Severe Debt and Impending Insolvency: Debt Settlement
If you are facing overwhelming debt, are already significantly behind on payments, or are on the verge of bankruptcy, debt settlement might offer a quicker resolution to your debt burden. By paying a reduced principal, you could potentially be debt-free in 2-4 years, putting you on track for 2027. However, this speed comes at a significant cost to your credit score and potentially a tax liability on forgiven debt. It’s a more drastic measure for more drastic situations.
Key Considerations for the 2027 Timeline:
- Starting Point: The sooner you begin either process, the faster you’ll reach your debt-free goal by 2027. Delaying action only prolongs the struggle.
- Amount of Debt: Larger debt amounts will naturally take longer to resolve, regardless of the method.
- Financial Discipline: Both methods require commitment. Credit counseling demands consistent payments, while debt settlement requires you to save a lump sum.
- Risk Tolerance: Are you willing to endure severe credit score damage and potential lawsuits for the chance of paying less overall? Or do you prefer a more stable, albeit longer, path?
Beyond 2027: Long-Term Financial Health
While the immediate goal might be to achieve debt relief by 2027, it’s equally important to consider the long-term implications of your chosen strategy. Financial freedom isn’t just about eliminating debt; it’s about building a stable and prosperous future.
Credit Counseling and Long-Term Health
The financial education and budgeting skills acquired through credit counseling are invaluable for preventing future debt accumulation. By learning to live within your means, save for emergencies, and use credit responsibly, you set yourself up for sustained financial health beyond the DMP’s completion. Your credit score, while potentially taking a minor hit, will recover more quickly and robustly, allowing you to access favorable lending terms in the future.
Debt Settlement and Long-Term Health
While debt settlement can provide quick relief from an immediate debt crisis, the long-term impact on your credit score can be substantial. Rebuilding your credit after debt settlement requires significant effort and time. It might take several years post-2027 to regain access to affordable credit for major purchases like a home or car. Furthermore, without addressing the underlying spending habits that led to debt, there’s a risk of falling back into the same financial traps.
Making the Right Choice: A Step-by-Step Approach
Choosing between credit counseling and debt settlement, or indeed any of the available debt relief options, requires careful consideration. Here’s a structured approach to help you decide:
Step 1: Assess Your Financial Situation Honestly
Gather all your financial documents: bank statements, credit card statements, loan agreements, pay stubs, and budget. Calculate your total income, total expenses, and total unsecured debt. Determine if you can realistically afford to make minimum payments or if you are already falling behind.
Step 2: Understand Your Debt Types
Identify which of your debts are unsecured (credit cards, personal loans, medical bills) and which are secured (mortgages, auto loans). Remember that credit counseling and debt settlement primarily address unsecured debts.
Step 3: Evaluate Your Credit Score Impact Tolerance
How important is your credit score to your immediate and future plans? If you plan to apply for a mortgage, car loan, or need good credit for employment in the near future, protecting your credit score should be a priority, leaning you towards credit counseling. If your credit is already severely damaged, the additional impact of debt settlement might be less of a concern.
Step 4: Research Reputable Agencies and Companies
If considering credit counseling, look for non-profit agencies accredited by organizations like the National Foundation for Credit Counseling (NFCC) or the Financial Counseling Association of America (FCAA). For debt settlement, research companies thoroughly, check their track record, read reviews, and understand their fee structure. Be wary of any company that guarantees specific results or asks for large upfront fees.
Step 5: Seek Professional Advice
Before making a final decision, consult with a financial advisor or a credit counselor. They can provide unbiased advice tailored to your specific circumstances and help you understand the full implications of each option.
Alternatives to Credit Counseling and Debt Settlement
While credit counseling and debt settlement are prominent debt relief options, they are not the only ones. Depending on your situation, other strategies might be more appropriate:
Debt Consolidation Loan
If you have a good credit score and a stable income, you might qualify for a debt consolidation loan. This involves taking out a new loan (often with a lower interest rate) to pay off all your existing high-interest debts. You then have a single monthly payment, potentially reducing your overall interest costs and simplifying your finances. This can lead to faster relief without the severe credit impact of debt settlement, potentially clearing debt by 2027.
Balance Transfer Credit Cards
For those with excellent credit and manageable debt, transferring high-interest credit card balances to a new card with a 0% introductory APR can provide a window of time (12-21 months) to pay down debt without accruing interest. This requires discipline to pay off the balance before the promotional period ends.
Bankruptcy
In cases of extreme financial distress, where neither credit counseling nor debt settlement is viable, bankruptcy (Chapter 7 or Chapter 13) might be the only option. While it provides a fresh start, it comes with the most severe and long-lasting impact on your credit score and financial reputation.
DIY Debt Management
For those with discipline and a smaller amount of debt, a do-it-yourself approach can be effective. This involves creating a strict budget, cutting expenses, and using strategies like the debt snowball or debt avalanche method to pay off debts systematically. This route has no fees and no negative credit impact, but it requires significant personal commitment.
The Future of Debt Relief by 2027
As we approach 2027, the financial landscape will continue to evolve. Economic conditions, interest rates, and regulatory changes can all influence the effectiveness and availability of various debt relief options. Staying informed and proactive is key. The rise of financial technology (fintech) may also introduce new tools and platforms to help individuals manage and reduce their debt more efficiently.
Regardless of the specific method chosen, the core principles of financial wellness remain constant: responsible budgeting, mindful spending, and consistent effort towards debt repayment. The goal is not just to eliminate debt by a certain date but to build a resilient financial foundation for years to come.
Conclusion: Your Path to a Debt-Free 2027
Deciding between credit counseling and debt settlement, or any other debt relief options, is a deeply personal choice with significant financial implications. If your aim is to be debt-free by 2027, both methods offer a potential pathway, but they cater to different levels of financial distress and carry distinct consequences.
Credit counseling provides a structured, educational, and less credit-damaging route for those who can still manage their payments but need assistance with interest rates and organization. It’s a journey towards full repayment and improved financial literacy, with a typical timeline of 3-5 years.
Debt settlement, on the other hand, is a more aggressive strategy for individuals facing severe debt and potential insolvency. It offers the possibility of paying less than the full amount owed and a potentially quicker resolution (2-4 years), but at the expense of significant credit score damage and other risks.
Ultimately, the fastest path to debt relief by 2027 is the one that best fits your unique circumstances, financial goals, and risk tolerance. Take the time to assess your situation thoroughly, understand all your available options, and seek professional guidance to make the choice that will lead you to a healthier, debt-free financial future. Your journey to financial freedom starts with an informed decision today.