New Medical Debt Protections: Federal Rules Limit Collections April 2026
The landscape of healthcare finance is undergoing a monumental shift, bringing much-needed relief to millions of Americans burdened by medical expenses. Effective April 2026, a series of new federal rules will introduce robust medical debt protections, fundamentally altering how healthcare providers and debt collectors interact with patients regarding outstanding medical bills. These regulations are designed to curb aggressive collection practices, enhance patient rights, and ultimately, prevent medical debt from devastating personal finances and credit scores. Understanding these changes is paramount for every consumer, as they promise to reshape the patient experience and offer a clearer path to financial stability in the face of illness.
Understanding Medical Debt Protections: New Federal Rules in Effect Since April 2026 Limiting Collection Practices and Improving Patient Rights
Medical debt has long been a pervasive and often crippling issue in the United States, pushing countless families into financial hardship, even bankruptcy. It’s a unique type of debt, often incurred unexpectedly and through no fault of the individual, making the existing collection methods particularly harsh. Recognizing this systemic problem, federal agencies have intervened, enacting comprehensive medical debt protections that will soon offer a significant reprieve. This article delves into the specifics of these new rules, exploring their implications for patients, healthcare providers, and the broader financial ecosystem.
The Pre-2026 Landscape: A Brief Overview of Medical Debt Challenges
Before we explore the new federal rules, it’s crucial to understand the environment that necessitated such drastic changes. For years, medical debt has been a leading cause of personal bankruptcy in the U.S. Unlike other forms of debt, medical bills are often opaque, complex, and arrive unexpectedly. Patients frequently find themselves caught in a labyrinth of insurance claims, deductibles, and out-of-network charges, leading to bills they never anticipated.
The Impact on Credit Scores and Financial Well-being
One of the most significant consequences of medical debt has been its detrimental effect on credit scores. Even small, unpaid medical bills could appear on credit reports, lowering scores and making it harder for individuals to secure loans, housing, or even employment. This disproportionately affected vulnerable populations, creating a vicious cycle of financial instability.
Aggressive Collection Practices
Furthermore, the collection of medical debt has often been characterized by aggressive and sometimes unethical practices. Patients reported receiving incessant calls, threats, and even lawsuits over bills they were still disputing or attempting to resolve with their insurance companies. The lack of clear regulations often left consumers feeling powerless against large healthcare systems and powerful collection agencies.
The absence of strong medical debt protections meant that a single medical emergency could derail a family’s financial future, regardless of their proactive efforts to manage their health and finances. This stark reality underscored the urgent need for federal intervention and the establishment of clearer, fairer guidelines for handling medical debt.
Key Pillars of the New Federal Medical Debt Protections Effective April 2026
The new regulations, set to take effect in April 2026, represent a multi-faceted approach to addressing the challenges of medical debt. These rules are primarily focused on limiting the reporting of medical debt to credit bureaus, restricting certain collection tactics, and empowering patients with more information and recourse. Let’s break down the core components of these transformative medical debt protections.
1. Prohibition of Medical Debt on Credit Reports for Paid and Low-Balance Debts
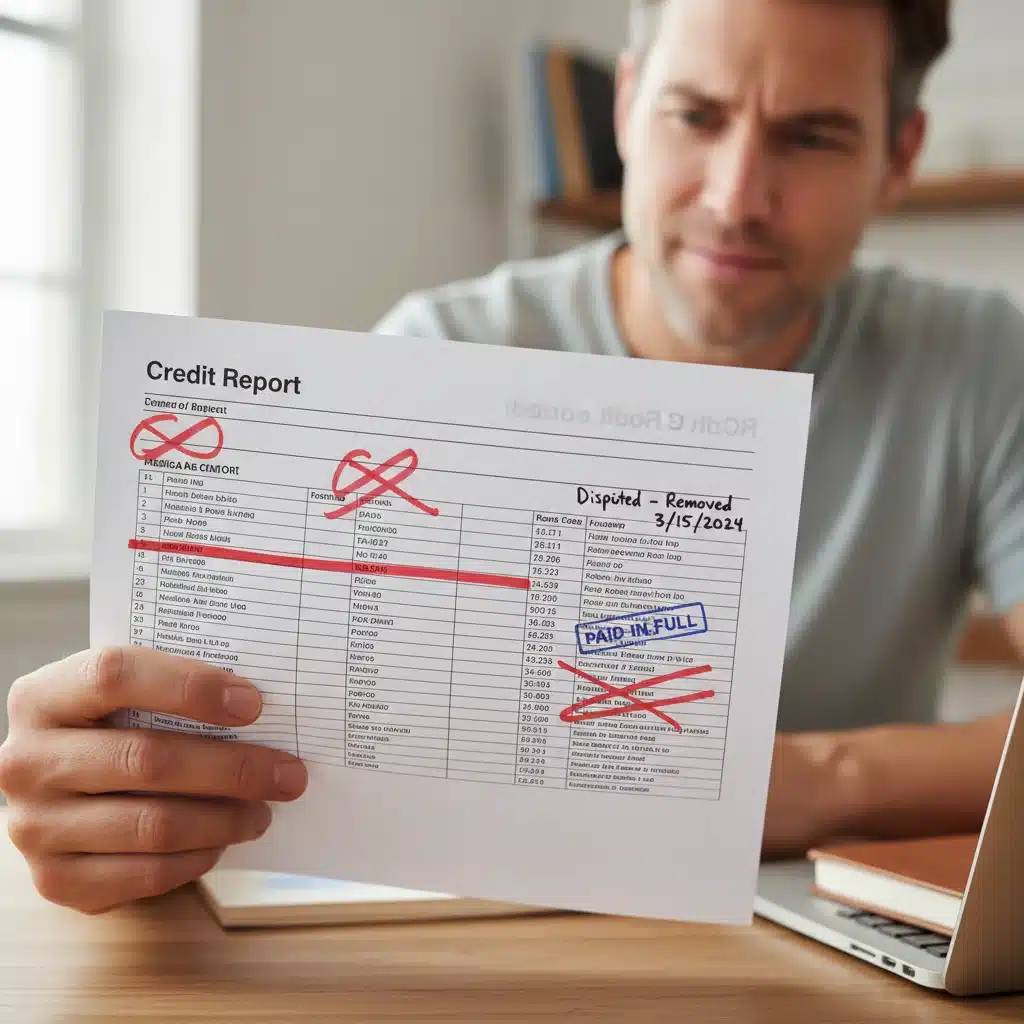
One of the most impactful changes is the prohibition of reporting paid medical debt to credit bureaus. Previously, even after a medical bill was settled, its prior existence as unpaid debt could linger on a credit report, negatively affecting scores. The new rules ensure that once a medical debt is paid, it must be removed from credit reports. Additionally, medical debts under a certain threshold (often $500, though this can vary by specific regulation and implementation) will also be prevented from appearing on credit reports, regardless of their payment status. This crucial step aims to prevent minor medical expenses from disproportionately harming creditworthiness.
2. Extended Waiting Period Before Reporting Unpaid Medical Debt
The new regulations introduce an extended waiting period before any unpaid medical debt can be reported to credit bureaus. This period, typically at least one year, allows patients ample time to resolve billing disputes, navigate complex insurance claims, and explore financial assistance options. This delay acknowledges the often-protracted nature of medical billing and dispute resolution, offering a much-needed buffer for consumers before their credit is impacted.
3. Enhanced Transparency and Information Requirements for Providers
Healthcare providers will be subject to stricter requirements regarding transparency. This includes providing patients with clear, itemized bills in a timely manner, explaining charges, and informing them about available financial assistance programs (such as hospital charity care policies). The goal is to ensure patients fully understand their financial obligations and their options for managing them, preventing unexpected bills from spiraling into unmanageable debt.
4. Restrictions on Aggressive Collection Practices
The new rules also place significant restrictions on the types of collection practices that can be employed for medical debt. While specific details may vary depending on the regulatory body (e.g., Consumer Financial Protection Bureau, Department of Health and Human Services), the general intent is to curb harassment, deceptive practices, and undue pressure on patients. This could include limitations on the frequency of calls, clearer communication requirements, and stricter penalties for violations.
5. Improved Access to Financial Assistance and Charity Care
A central tenet of the new medical debt protections is to ensure that eligible patients have better access to financial assistance and charity care programs. Hospitals, particularly non-profit ones, often have policies in place to provide free or discounted care to low-income individuals. The new rules aim to make these programs more visible and accessible, requiring providers to proactively inform patients about them and streamline the application process.
These five pillars collectively form a robust framework designed to protect consumers from the most damaging aspects of medical debt, fostering a fairer and more equitable healthcare financial system. The implementation of these medical debt protections in April 2026 marks a pivotal moment for patient advocacy and financial well-being.
Who Benefits Most from These Medical Debt Protections?
While these new federal rules are designed to benefit all consumers, certain groups stand to gain significantly more from the enhanced medical debt protections.
Low-Income Individuals and Families
Those with limited financial resources are often the most vulnerable to the devastating effects of medical debt. The provisions relating to financial assistance, charity care, and the prohibition of reporting low-balance debts will be particularly impactful for this demographic, preventing minor health issues from escalating into major financial crises.
Individuals with Chronic Illnesses
Patients managing chronic conditions often incur frequent and substantial medical expenses. The extended waiting period before debt reporting and the emphasis on transparent billing will provide much-needed breathing room and clarity, allowing them to focus on their health rather than constantly battling unexpected bills.
Those Facing Unexpected Medical Emergencies
Medical emergencies can strike anyone, regardless of income or insurance status. The new rules offer a safety net, ensuring that an unforeseen accident or illness doesn’t immediately lead to a damaged credit score or aggressive collection efforts, giving individuals time to recover and sort out their finances.
Anyone with a Medical Bill Dispute
The extended reporting period and emphasis on transparency will greatly assist individuals who are actively disputing a medical bill with their provider or insurance company. It provides a crucial window to resolve discrepancies without the immediate threat of credit damage.
Practical Steps for Consumers Under the New Rules
Even with these new medical debt protections in place, proactive engagement remains key for consumers. Here are practical steps you can take to leverage these new rules and protect yourself:
1. Review All Medical Bills Carefully
Always scrutinize every medical bill you receive. Check for accuracy, ensure services billed were actually rendered, and verify that your insurance has been properly applied. Don’t hesitate to request an itemized bill if you only receive a summary statement.
2. Understand Your Insurance Coverage
Familiarize yourself with your health insurance plan’s deductibles, co-pays, and out-of-pocket maximums. Knowing what your insurance covers (and doesn’t cover) can help you anticipate costs and identify billing errors.
3. Communicate with Your Provider
If you receive a bill you don’t understand or can’t afford, contact the hospital or provider’s billing department immediately. Many institutions are willing to negotiate payment plans or discuss financial assistance options. Under the new rules, they are also obligated to inform you about these options.
4. Explore Financial Assistance and Charity Care
Inquire about your healthcare provider’s financial assistance or charity care policies. These programs can significantly reduce or even eliminate your medical debt if you meet their eligibility criteria. The new regulations aim to make these programs more transparent and accessible.
5. Monitor Your Credit Report
Regularly check your credit report from all three major bureaus (Equifax, Experian, TransUnion) through AnnualCreditReport.com. This allows you to identify any medical debts that might have been improperly reported and dispute them promptly. Remember, under the new rules, paid medical debts and low-balance debts should not appear.
6. Document Everything
Keep meticulous records of all communications with healthcare providers, insurance companies, and debt collectors. This includes dates, times, names of individuals you spoke with, and a summary of the conversation. This documentation can be invaluable if you need to dispute a bill or report a violation of the new medical debt protections.
7. Know Your Rights Regarding Collection Agencies
Be aware of your rights under the Fair Debt Collection Practices Act (FDCPA) and any additional protections offered by the new federal rules. If a collection agency engages in harassing or deceptive practices, you have the right to report them to the appropriate regulatory bodies.
The Role of Healthcare Providers and Insurers
The implementation of these new medical debt protections isn’t just about patient rights; it also places significant responsibilities on healthcare providers and insurance companies. They will need to adapt their billing practices, communication strategies, and internal processes to comply with the new regulations.
For Healthcare Providers:
- Updated Billing Systems: Providers will need to ensure their billing systems can accurately track payment status and automatically remove paid debts from any potential reporting to credit bureaus.
- Enhanced Financial Counseling: There will be a greater emphasis on providing comprehensive financial counseling to patients, explaining costs upfront, and proactively offering information on financial assistance programs.
- Training for Staff: Billing and administrative staff will require extensive training on the new rules to ensure compliance and provide accurate information to patients.
- Streamlined Charity Care Applications: Hospitals will need to simplify the application process for charity care and make eligibility criteria more transparent.
For Insurance Companies:
- Faster Claims Processing: While not directly mandated by these specific rules, faster and more transparent claims processing from insurers would significantly reduce the likelihood of disputed or delayed medical bills turning into debt.
- Clearer Explanation of Benefits (EOB): Insurers can further assist patients by providing clearer and more understandable Explanation of Benefits (EOBs) that detail what was covered, what was denied, and why.
Collaboration between providers, insurers, and patients will be crucial for the successful implementation and positive impact of these new medical debt protections.
Addressing Potential Challenges and Unintended Consequences
While the new medical debt protections are overwhelmingly positive, it’s important to consider potential challenges and unintended consequences during their rollout and beyond.
Compliance Burdens for Smaller Providers
Smaller healthcare practices and rural hospitals might face challenges in updating their billing systems and training staff to comply with the new regulations. Federal agencies may need to provide clear guidance and resources to ensure equitable implementation across all types of healthcare entities.
Impact on Hospital Revenue Cycles
With longer waiting periods before debt can be reported and increased access to financial assistance, some healthcare providers might experience changes in their revenue cycles. This could potentially lead to adjustments in their financial strategies, though the long-term goal is to create a more stable and predictable system.
Patient Education and Awareness
The effectiveness of these new rules heavily relies on patient awareness. If individuals are not informed about their new rights and the available protections, the impact will be limited. Ongoing public education campaigns will be vital to ensure that consumers can fully leverage these new safeguards.
Enforcement and Oversight
Robust enforcement mechanisms will be critical to ensure that healthcare providers and debt collectors adhere to the new regulations. Regulatory bodies must be equipped to investigate complaints and levy appropriate penalties for non-compliance, thereby reinforcing the integrity of these medical debt protections.
Looking Ahead: The Future of Medical Debt in America
The implementation of these federal rules in April 2026 marks a significant milestone in the ongoing effort to reform healthcare finance. These medical debt protections are not a panacea for all healthcare cost issues, but they represent a substantial step forward in shielding consumers from the most punitive aspects of medical debt.
Beyond these immediate changes, the conversation around medical debt is likely to continue evolving. Future discussions may focus on:
- Price Transparency: Further measures to ensure upfront price transparency for medical procedures and services.
- Surprise Billing: Expanding protections against surprise medical bills, particularly from out-of-network providers.
- Standardization of Billing: Efforts to simplify and standardize medical billing practices across the industry.
- Preventative Care Emphasis: Policies that further emphasize preventative care to reduce the incidence of costly medical emergencies.
The overarching goal is to create a healthcare system where individuals can seek necessary medical care without the constant fear of financial ruin. These new medical debt protections are a foundational element in building that more equitable and sustainable future.
Conclusion: A New Era for Patients Facing Medical Debt
The upcoming federal rules, effective April 2026, usher in a new era for patients grappling with medical debt. By introducing comprehensive medical debt protections, the government is taking decisive action to limit aggressive collection practices, enhance transparency, and safeguard the financial well-being of millions of Americans. These regulations promise to remove the specter of medical debt from credit reports for paid and low-balance bills, provide crucial time for dispute resolution, and ensure greater access to financial assistance. While challenges in implementation may arise, the long-term benefits of these protections are poised to create a fairer, more compassionate healthcare financial landscape. As consumers, staying informed and proactive will be essential to fully harness the power of these new rights and secure a more stable financial future.